Whether you are buying a Cliffe townhouse or remortgaging in Wallands, we can work by phone, video or in person. Get in touch for a free, no obligation chat.
Lewes has more than 500 listed buildings in its conservation area, sits inside the South Downs National Park and is barely an hour from London Victoria. It is also one of the trickiest places in Sussex to mortgage a home - which is exactly why whole of market advice matters here.


£131m+
Mortgages arranged since 2024
1,400+
Clients helped
Whole of market
Independent mortgage brokers
Free
No obligation consultation
10,000+
Mortgage products
90+
Lenders searched
Whether you are buying a Cliffe townhouse or remortgaging in Wallands, we can work by phone, video or in person. Get in touch for a free, no obligation chat.
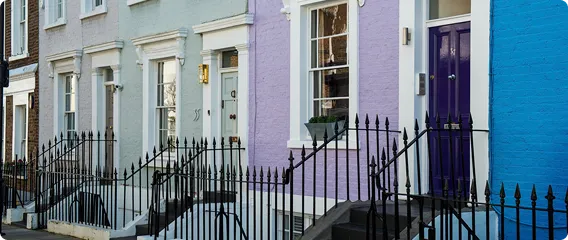
Lewes is the county town of East Sussex, and its housing stock reflects six centuries of building. The conservation area alone contains 504 listed buildings - eight Grade I, 21 Grade II* and 475 Grade II - and the town is built from flint, Sussex brick, weatherboarding, mathematical tiles and timber frame, with one High Street property dated to 1330. For a lender, all of that reads as non-standard construction, and a good number of mainstream banks will simply decline. Quanstrom Financial works on a whole of market basis, so we can approach lenders who understand period and listed property rather than accepting the first no. We advise across Cliffe, Southover, Wallands, South Malling, Nevill and Landport.

Lewes is the most expensive town we cover - the average sale sits above £540,000, and even terraced houses average around £548,000, more than a detached house in most of the surrounding towns. Around 34 direct trains a day reach London Victoria in roughly one hour and ten minutes, which underpins that premium. Whether you are buying, moving up, remortgaging or investing, we can outline what may be achievable on your income and deposit, subject to lender criteria.
Land Registry sold price data puts the average Lewes town sale at around £540,000 over the past year, up roughly 2% on a year earlier - a resilient market underpinned by limited supply. Semi-detached homes average around £613,000, terraced houses around £548,000 and flats around £258,000. Note that the wider Lewes district average, which includes Newhaven, Peacehaven and Seaford, is far lower at around £368,000: the town itself carries a substantial premium over the district it names.
Two things sustain that premium. The first is the train - London Victoria in a little over an hour, plus fast services to Brighton. The second is scarcity: Lewes sits within the South Downs National Park, which sharply limits new development, and the historic core is almost entirely conservation area. Prices vary street by street, with Southover, Cliffe and the roads climbing towards Wallands generally strongest, while Landport and parts of Malling offer more accessible options.
The main new supply in the pipeline is the North Street Quarter, known as The Phoenix, a 15 acre brownfield riverside scheme by Human Nature planned for 416 homes with 40% affordable. Harveys Brewery remains in the town centre and Glyndebourne lies about four miles east. These figures are rounded averages and move over time; treat them as a guide rather than a valuation.
We are here to guide you through the process and help you secure the right residential mortgage for your needs. Whether you are a first time buyer, home mover or looking to remortgage a property, we will help you understand your options and keep everything on track.

Taking your first step onto the property ladder is a big milestone. We explain each stage in plain English, help you understand how much you can borrow and which lenders are suitable, and support you from Agreement in Principle through to getting your keys.

If you are considering a buy to let, Quanstrom Financial will help you find a mortgage that supports your investment strategy. We work with landlords at every level, from first time investors to those with larger portfolios, and focus on finding competitive products that work hard for you.
In Lewes the property itself is often the obstacle, not the borrower. A listed cottage, a flint wall, a timber frame or a flat above a High Street shop can all reduce your choice of lender to a handful - and which handful depends on the specific building. Quanstrom Financial searches the whole market rather than one panel, tells you plainly where a case is likely to sit, and manages the back and forth with lenders, solicitors and surveyors.
Meet the team at Quanstrom Financial and learn about us.
Often yes, but the field narrows. Lenders consider the grade, condition, construction and any restrictions on alterations, and several mainstream lenders decline listed property outright. Whole of market advice makes a real difference here.
Lenders class these as non-standard construction, which reduces the number willing to lend but rarely rules a property out. Some lenders are very comfortable with traditional Sussex construction; we know which tend to be.
The direct London train, the schools and the town's character all play a part, but scarcity is the biggest factor. National Park and conservation area status keep new building limited, which supports values.
Yes. Flats above commercial premises reduce the number of available lenders, and the type of business below can matter too. It is worth checking lender appetite before you make an offer.
Meet the team at Quanstrom Financial and learn how we can help with your mortgage. Whether you prefer a quick call, an email or an online enquiry, we are ready to help you get started.
From the blog

Book Your Free Consultation
Get in touch