Bad credit mortgages

Adverse credit mortgages

A CCJ, default, missed payment, debt management plan, IVA or past bankruptcy doesn't automatically rule you out of a mortgage. What matters is the type of issue, how long ago it happened, whether it's settled and your deposit, so choosing the right lender makes all the difference.

Written by Toby Quanstrom, Director, Quanstrom Financial · 4 November 2026

  • CCJs, defaults, missed payments, DMPs, IVAs and bankruptcy
  • Whole of market, including specialist lenders
  • Free first consultation, with no obligation

Recent case: a mortgage offer with Metro Bank for a buyer whose IVA had been satisfied three years earlier. Every case is different.

Your home may be repossessed if you do not keep up repayments on your mortgage.

5.0 from 230+ Google reviews

Book a free consultation

We aim to reply the same working day.

Prefer to pick a time?Choose a slot in our diary

We'll only use your details to respond to your enquiry. See our privacy policy.

The short answer

Can you get a mortgage with bad credit?

Yes, it may be possible. Very few credit problems rule you out completely. Lenders look at the type of issue, how big it was, how long ago it happened, whether it's been settled and how you've managed credit since. A bigger deposit can widen your options too.

Lenders take very different views of the same credit history. Some mainstream lenders may accept small, older, settled issues, while specialist lenders are set up to look at the fuller picture. Applying to the wrong lender first can mean a decline and another hard search on your file, so it pays to match your history to the right lender from the start.

What lenders look at

What lenders weigh up with adverse credit

Lenders don't just ask whether you have bad credit. They look at the detail, and the detail is often better than people expect.

The type and size of the issue

A £150 phone default is very different from a mortgage default or a large CCJ. Some lenders ignore small amounts entirely, particularly with utility and phone providers.

How long ago it happened

The older the issue, the less weight it carries. Many specialist lenders focus on the last one to three years, while many mainstream lenders look back over six.

Whether it's settled

A settled CCJ or default is a historic problem. An outstanding one is a live debt, and this is often the single biggest factor.

Your deposit and conduct since

A larger deposit offsets the risk and can open up more lenders. A clean record since the event is one of the strongest signals you can show.

What you may be able to borrow depends on your circumstances and lender criteria.

Lender comparison

How mainstream and specialist lenders compare

The same credit history can be a decline at one lender and an acceptance at another. Here's how a mainstream lender, Accord Mortgages, compares with specialist lenders on each type of credit issue.

Credit issueAccord Mortgages (mainstream)Specialist lender exampleWhat matters most
CCJsNo more than 1 CCJ, totalling £300 or less, registered in the last 6 yearsPepper Money: none in the last 6 months for up to 80% loan to value, rising to 90% with none in the last 36 monthsWhether it's satisfied, its size and how recent it is
DefaultsNo more than 2 defaults, totalling £250 or less, registered in the last 6 yearsPepper Money: none in the last 6 months for up to 80% loan to value, with up to 2 utility or phone defaults of £200 or less ignored on several productsIts size, the type of provider and whether it's settled
Missed paymentsSecured: no more than 1 missed payment on 1 account in the last 24 months. Unsecured: no more than 2 on 1 accountVida Homeloans: up to 3 unsecured missed payments in the last 6 months on its Vida 6 tierSecured or unsecured, how many and how recent
Debt management plansNone registered in the last 6 yearsBluestone Mortgages: an active plan may be considered, with no minimum time running statedActive or settled, and your payment record within it
IVAsSatisfied for a minimum of 6 yearsMelton Building Society: an active IVA may be considered on its Credit Recovery range if it's being conducted satisfactorilyWhether it's active, and how long since it was satisfied
BankruptcyDischarged for a minimum of 6 yearsBuckinghamshire Building Society: discharged for 3 years or more for up to 85% loan to value, or less than 3 years at underwriter discretion up to 75%Whether you're discharged, and how long ago

From each lender's published intermediary criteria: Accord and Pepper Money checked November 2026, the others August 2026. Criteria change often, other lenders take different views, and lending depends on your circumstances.

Compare more lenders in our guides to mortgages with a CCJ and mortgages with an IVA.

Time and your options

Does it matter how long ago it happened?

Yes, a great deal. As a general pattern, the more time that has passed since an issue was registered or settled, the more lenders may consider you, and the closer your options get to standard terms.

Within the last few years

Fewer lenders, mostly specialists, and a larger deposit is often needed. Even so, some specialists may consider CCJs and defaults from as little as six months ago.

Three to six years and beyond

A wider range of lenders becomes realistic, including some mainstream lenders for small, settled issues. After six years, most issues drop off your credit file altogether.

General patterns only, not an offer of credit. Every lender sets its own time periods, and lending depends on your circumstances.

Recent cases

How Quanstrom Financial has helped clients with adverse credit

A credit history that feels serious to you can look quite different to the right lender. Two recent examples:

£840 of old defaults, still a high street lender

Chris wanted to buy his first home for £380,000 with a 10% deposit. He had four small defaults totalling £840, settled three years earlier. Because they were small and fully repaid, Quanstrom Financial secured him a mortgage offer with NatWest.

Eastbourne · first-time buyer

£9,000 of defaults and recent missed payments

Angela was buying for £375,000 with a 15% deposit. She had £9,000 of defaults registered two years earlier and paid off four months before, plus seven missed card payments in the last year. Most of the defaults were with utility providers, which some lenders disregard, and we secured her a mortgage offer with Bluestone.

Brighton · home purchase

Names changed. Every case is different, and lending depends on your circumstances and lender criteria.

Your advisers

Your adverse credit mortgage advisers

You'll deal with the same small team from your first call through to completion.

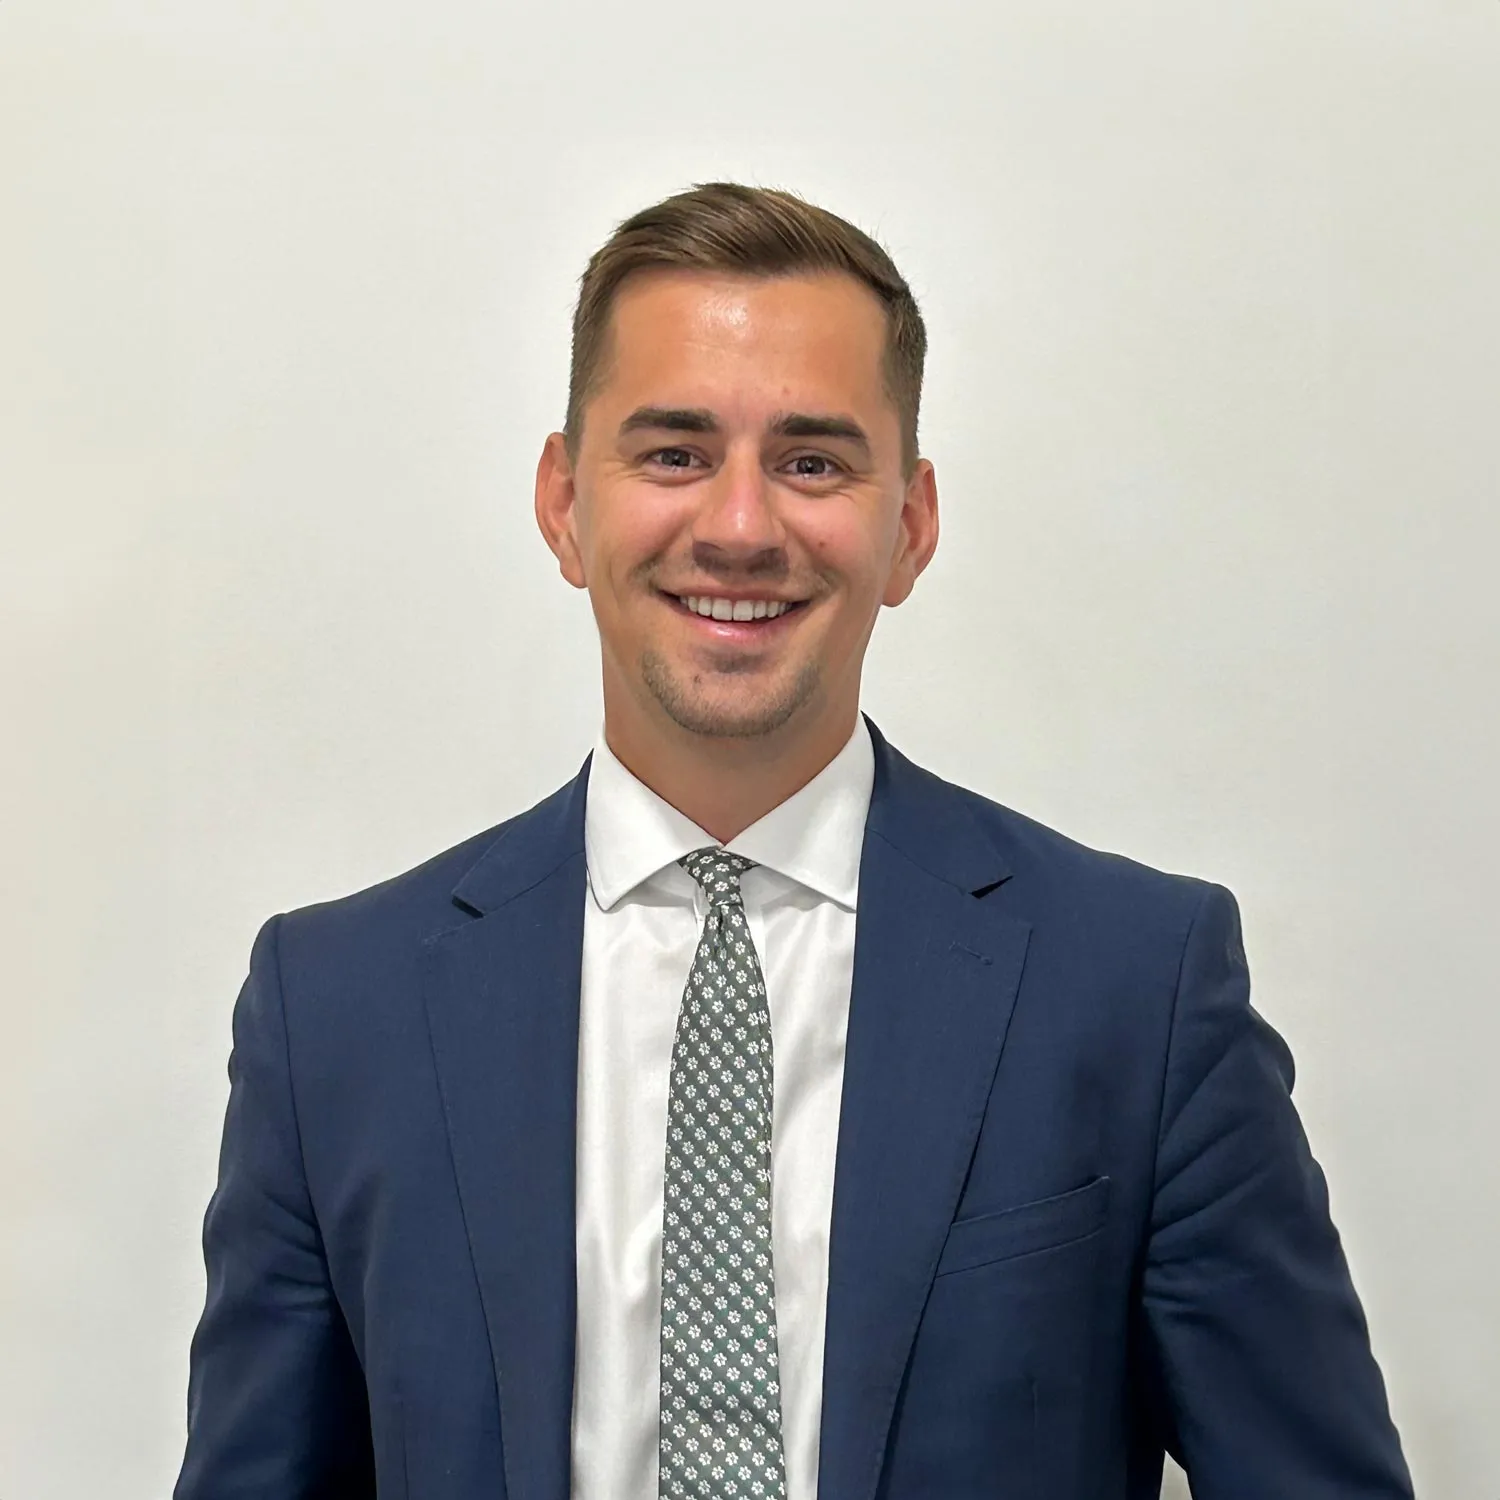
Toby Quanstrom

Toby Quanstrom

Director and Mortgage Adviser

Over a decade in mortgages and protection, from high-street banks to a corporate brokerage, before setting up Quanstrom Financial. He knows which lenders take a fair view of a difficult credit history.

Speak to Toby →
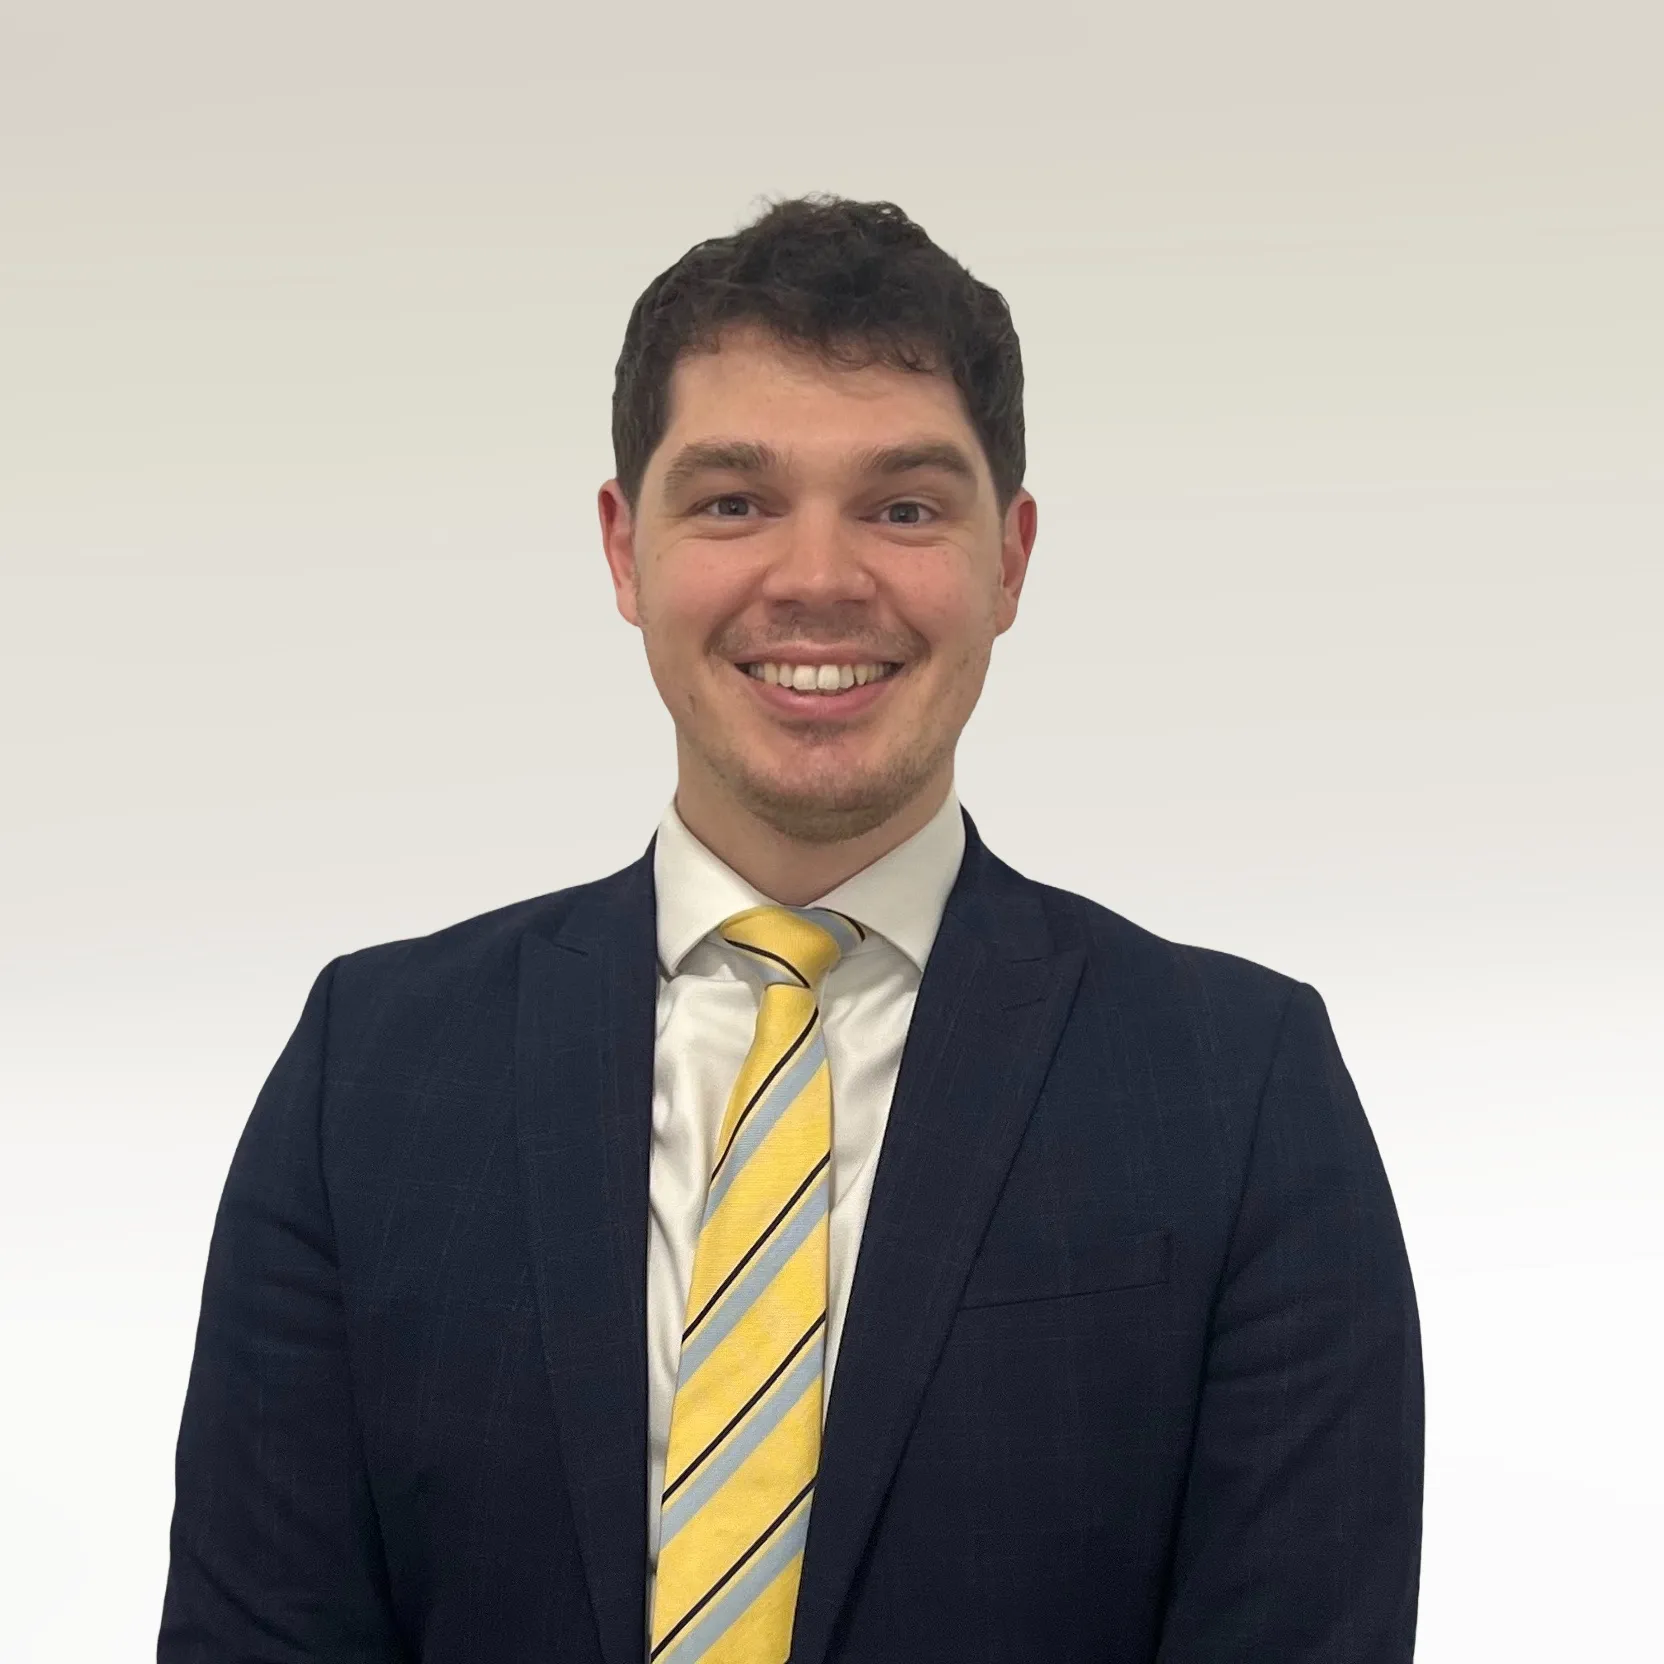
Will Harrington

Will Harrington

Mortgage and Protection Adviser

Will spent over a decade as an estate agent in Eastbourne before becoming a mortgage adviser, so he understands the buying process from both sides.

Speak to Will →
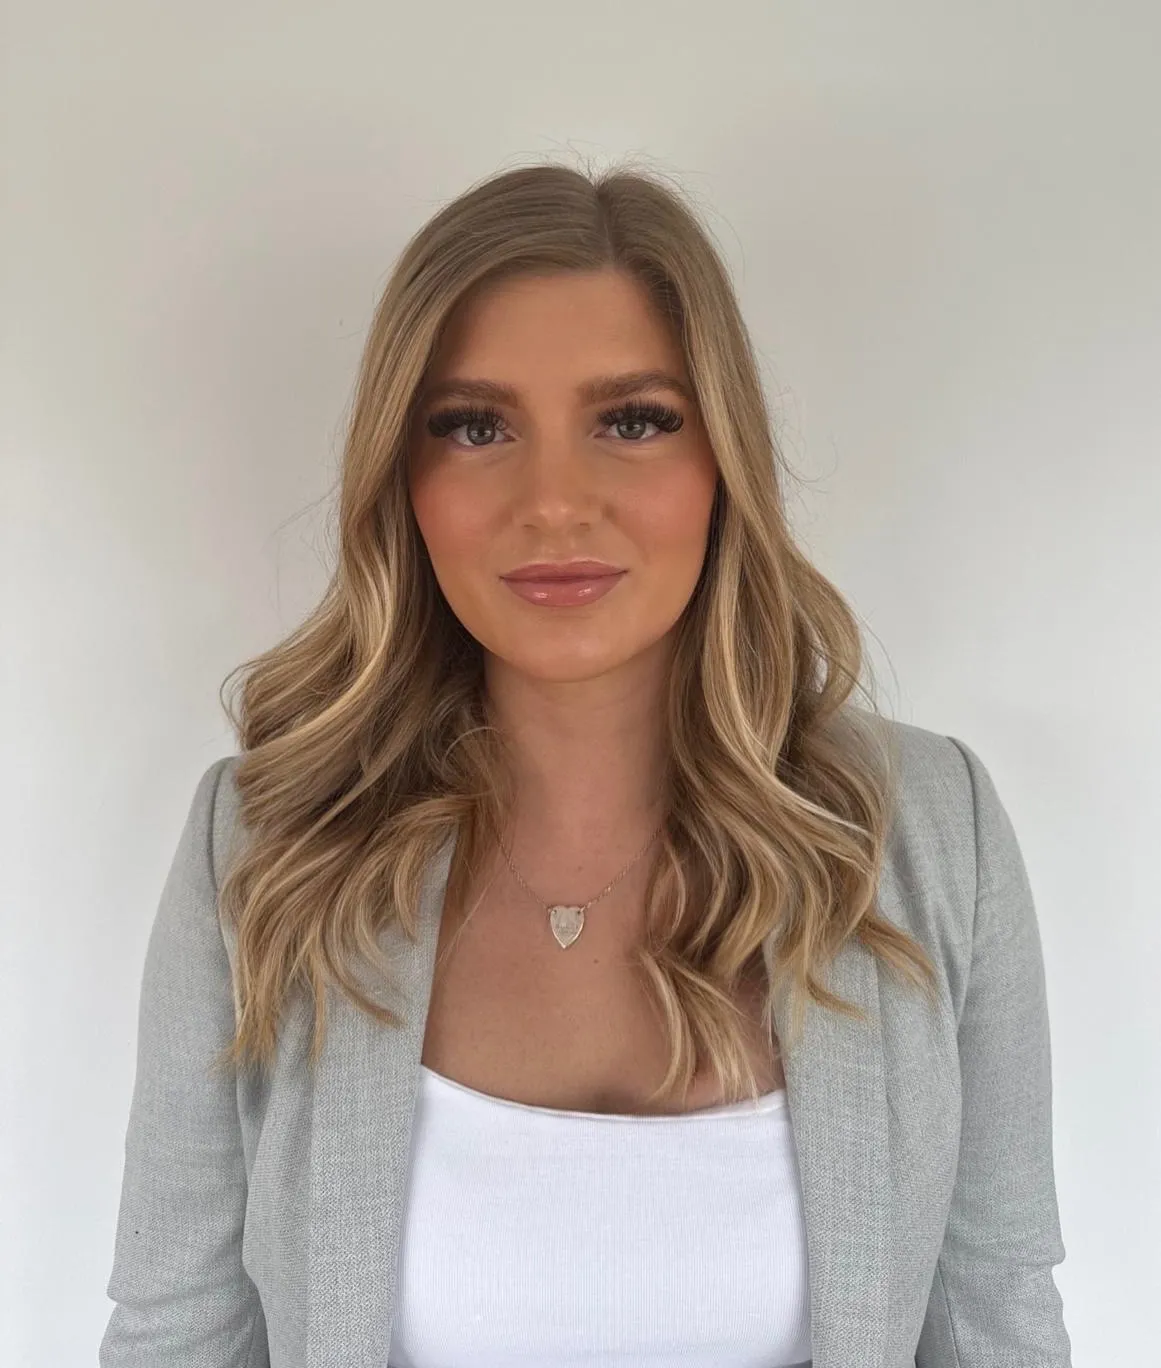
Jessica Giddins

Jessica Giddins

Case Manager

Known to clients as Jessie, she manages every application from submission to completion, keeping you, your solicitor and your estate agent up to date.

Why Quanstrom Financial

Why clients with credit problems choose Quanstrom Financial

  • No judgement, just optionsCredit problems happen for all sorts of reasons. We look at what's actually on your file and explain which lenders may consider it.
  • £145m+ arranged since 2024More than 1,400 clients helped, and rated 5.0 from 230+ Google reviews.
  • Lenders you can't go to directlyMany specialist lenders that consider adverse credit only accept applications through brokers.
  • Your case managed start to finishJessie keeps your application moving with the lender and your solicitor, so you always know where things stand.

One of the many things that sets him apart is immediately understanding the key elements of my situation and applying his expertise to find a rapid solution.

Toby QuanstromDan C., about TobyGoogle review

How it works

How it works

Five steps from your first call to completion. Quanstrom Financial handles the paperwork along the way.

  1. Free initial chat

    Tell us what's on your credit file, when it happened and whether it's settled. We'll explain which types of lender may consider it.

  2. Check your credit reports

    Get your reports from Experian, Equifax and TransUnion, so we work from what lenders will actually see rather than memory.

  3. Compare the market

    We compare 90+ lenders, including specialists that only work through brokers, and recommend a mortgage that suits your history, explaining why.

  4. Application and offer

    Jessie submits your application and keeps it moving with the lender until your mortgage offer is issued.

  5. Completion

    Your solicitor completes the legal work, and you move in or your new deal starts.

Local and nationwide

Adverse credit mortgages in Eastbourne, Sussex and across the UK

Quanstrom Financial is based in Eastbourne and helps clients with CCJs, defaults, missed payments, DMPs, IVAs and past bankruptcy across East and West Sussex, Kent and the rest of the UK, by phone and video, or in person by arrangement.

Protect your income and your homeA mortgage is a long commitment. Life insurance and income protection could help keep up your repayments if you can't work. There's no charge for our protection advice.Protection options

Questions about adverse credit mortgages

Can't see your question? Call us on 01323 364432 or book a free consultation.

Can I get a mortgage with bad credit?

Yes, it may be possible. Very few credit problems rule you out completely. Lenders look at the type of issue, its size, how long ago it happened, whether it's settled and your deposit. Specialist lenders are set up for more recent or serious issues, and some mainstream lenders may accept small, older ones.

Which lenders accept adverse credit?

Mainstream lenders such as Accord may accept small, older and settled issues within set limits. Specialist lenders such as Pepper Money, Bluestone Mortgages and Vida Homeloans are set up to consider more recent or more serious credit problems. Many specialist lenders only accept applications through brokers.

How much deposit do I need with bad credit?

It depends on how serious and how recent the issue is. Pepper Money, for example, may lend up to 90% of the property value where there have been no CCJs or defaults in the last 36 months, and up to 80% where there have been none in the last 6 months. More serious issues usually need a larger deposit.

How far back do mortgage lenders look at your credit history?

Most credit issues stay on your credit file for six years. Many mainstream lenders look at the full six years, while specialist lenders often focus on the last one to three years. Accord, for example, looks at CCJs and defaults registered in the last six years.

Can I remortgage with bad credit?

Often, yes. If you switch to a new deal with your existing lender, a product switch, there are usually no credit or income checks. Moving to a new lender, or borrowing more, is a full application where your credit history is assessed in the same way as a purchase.

Will I pay a higher interest rate with bad credit?

Often, but not always. Small, older and settled issues may be accepted on a mainstream lender's usual products. Specialist lenders usually charge more, but rates tend to improve as the issue ages and your deposit grows, and many people move to a mainstream lender when they remortgage later.

Will speaking to you affect my credit score?

No. Our first conversation doesn't involve a credit search. Lenders search your file when you apply, so we aim to match you to the right lender before any application, rather than collecting declines and hard searches along the way.

How much does your advice cost?

Fees vary depending on your circumstances. Get in touch and we'll explain any costs clearly before you proceed. Your first consultation is free and there's no obligation.

Worried about your credit history?

Tell us what's on your file and when it happened. We'll explain which lenders may consider you, with no judgement and no obligation. Your first consultation is free.

Book your free consultation

or call 01323 364432

Estate agent? Refer a client

Your home may be repossessed if you do not keep up repayments on your mortgage.

Chat with Quanstrom Financial on WhatsApp
CallBook a free consultation